
Steve Hourigan is founder and CEO of HeardSafe, Inc., which builds governance signal infrastructure, and has served on more than twenty boards. Full bio at the end of the article.
Key Takeaways
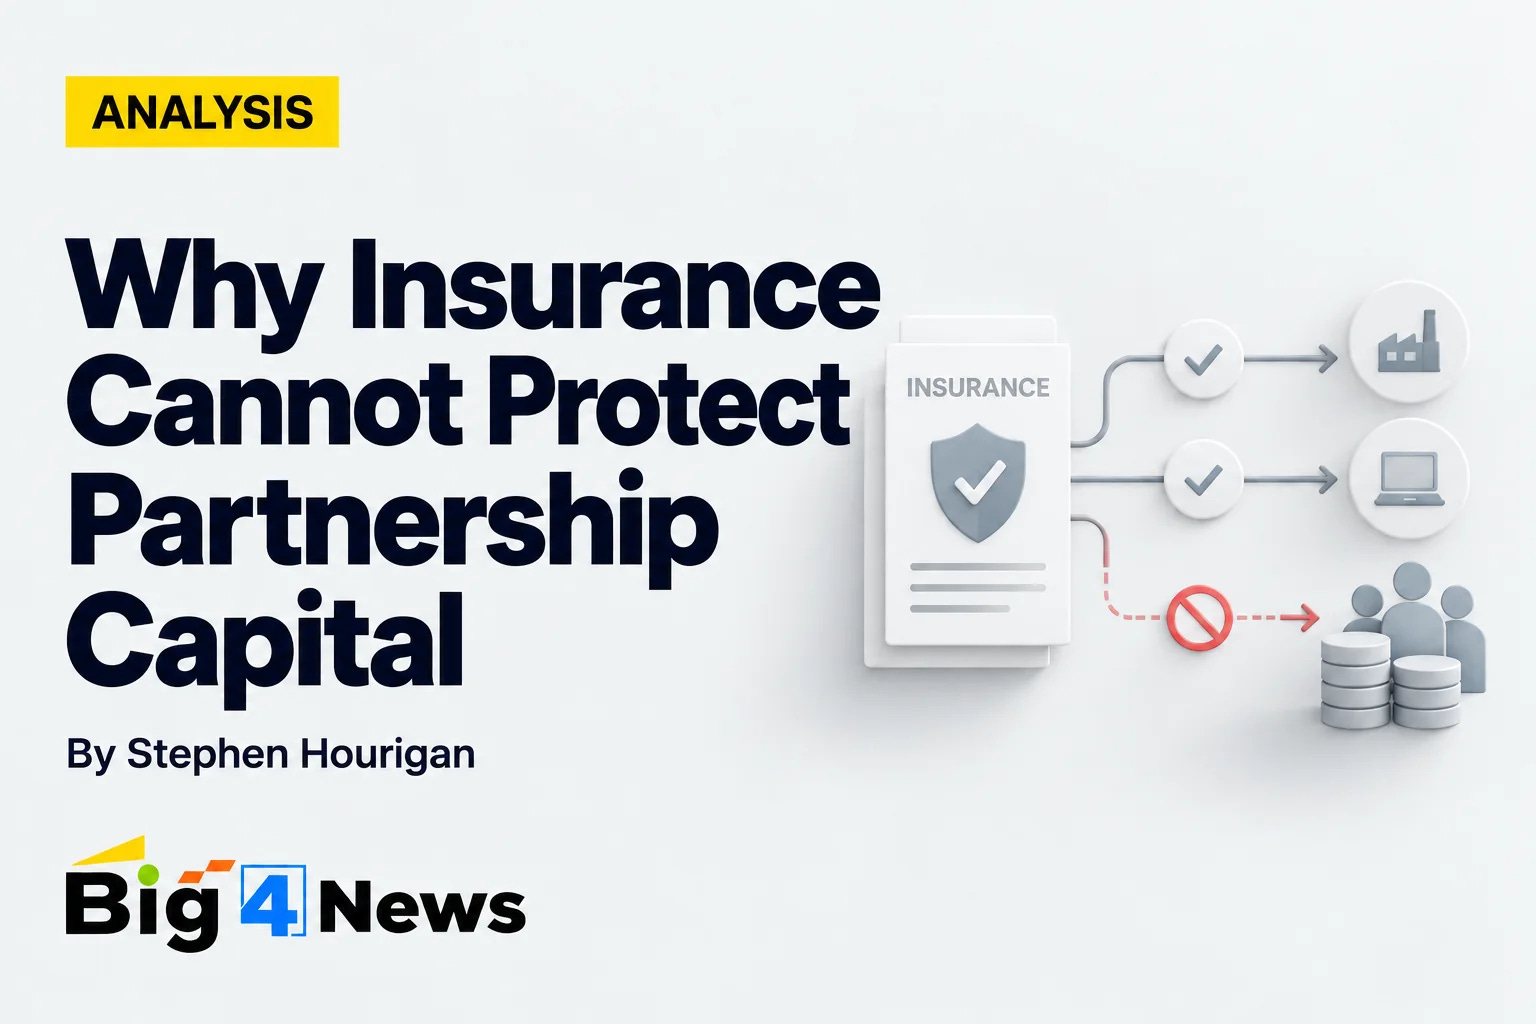
Insurance has limits. Professional indemnity coverage may finance legal claims, but it cannot protect Big Four firms against lost clients, damaged reputations or declining earnings.
Governance failures create capital pressure. Uninsured liabilities, captive insurance obligations, lost earnings and financing needs can combine to weaken a partnership’s financial position.
PwC and KPMG illustrate the risks. The Evergrande scandal and KPMG Australia’s recent controversies show how governance failures can have commercial consequences beyond fines and settlements.
International networks may face exposure. Financial difficulties at individual member firms can create pressure for support from the wider Big Four network.
Early intervention matters. Identifying, escalating and resolving governance problems before they escalate may be as important as securing insurance coverage.
The real cost begins where insurance protection ends
When a major accounting firm experiences a governance failure, attention typically turns to regulatory fines, litigation, professional indemnity insurance and the eventual settlement. These capture only part of the damage. For a Big Four partnership, the more consequential exposure may emerge afterward: clients depart, future engagements disappear, partners retain capital that might otherwise be distributed, lenders reconsider credit exposure, and international network organizations face pressure to support a weakened member firm.
Professional indemnity insurance and captive arrangements finance defined liabilities. They are not designed to preserve the entire economic value of a professional-services franchise. Recent controversies involving PwC and KPMG demonstrate how governance deterioration can migrate from an operational failure into a much broader capital problem.
Defining Governance Capital Stress
Governance Capital Stress (GCS) measures the incremental capital and earnings burden associated with governance deterioration.
The proposed framework examines four interacting dimensions of financial stress:
GCS: IRLC | CCE | EFS | LCC
IRLC — Incremental Retained Liability Capital: uninsured or unrecovered claims, deductibles, settlements, regulatory penalties and other liabilities.
CCE — Captive Capital Exposure: incremental reserves, capital impairment, collateral requirements and additional captive funding obligations.
EFS — External Financing or Support Required: incremental financing, liquidity facilities, guarantees or international-network assistance needed to maintain financial continuity.
LCC — Lost Client Contribution: earnings contribution lost through terminated engagements, abandoned appointments, procurement restrictions and impaired future business.
These dimensions interact but are not necessarily additive: some represent economic losses, while others represent capital requirements or financing responses. They must be assessed over a defined period, with care taken to avoid double counting. A network loan that finances an already recognized loss is a liquidity response, not a second economic loss. Contingent claims must be distinguished from established liabilities and insurance recoveries reconciled.
Why captives cover only part of the economic problem
The Big Four combine partnership retentions, captive insurance arrangements and external professional indemnity (PI) coverage. A captive may finance retained layers of eligible professional-liability claims and coordinate risk financing across participating entities. But its protection is narrower than the economic consequences of governance failure. Lost audit clients, restrictions on government procurement, impaired advisory demand and increased financing costs generally do not constitute covered professional-liability claims. Regulatory penalties may also be excluded or uninsurable under applicable law.
In shared international captive structures, a claim originating in one jurisdiction may affect reserves and funding obligations across participants, depending on the ownership and contractual arrangements. The captive may finance a covered liability without restoring the client confidence or earnings capacity lost by the operating firm.
Exhibit 1 | Governance Capital Stress: Who Bears the Cost?
Illustrative allocation following a major Big Four governance failure; actual responsibility depends on policies, contracts and law.
GCS cost categoryCaptive / external PIOperating partnershipInternational networkProfessional claims and settlementsPotentially covered, subject to limitsRetentions and uninsured amountsPossible shortfall supportRegulatory penaltiesOften excluded or uninsurablePrimary burdenPossible liquidity supportLegal defense / investigationsEligible costs may be coveredUncovered expensesPossible supportCaptive reserve strengtheningCaptive reserves / capital at riskFunding or collateral callsPossible shared exposureLost clients and contributionGenerally not coveredLost future earningsIndirect network impactProcurement restrictionsGenerally not coveredLost future businessIndirect network impactHigher PI costs and retentionsNot reimbursed as operating costIncreased future costsPotential networkwide effectLiquidity / financing pressureGenerally not coveredBorrowing and retained distributionsPossible loans or guarantees
Note: International support is a potential funding response, not an automatic obligation or necessarily an additional economic loss.
Exhibit 2 | Illustrative GCS financial waterfall
Governance failure → claims, penalties, lost clients and commercial disruption
↓ Covered claims → captive retained layer and external PI insurance, subject to policy terms
↓ Uninsured losses and residual claims → operating partnership earnings and capital
↓ Additional captive funding, collateral or liquidity needs → partnership resources
↓ If local resources are insufficient → potential international network loans, guarantees or contributions
The distinction is fundamental. Insurance may finance substantial eligible legal claims, but it does not insure the entire partnership franchise. Lost client contribution, regulatory restrictions, additional financing costs and weakened future earnings generally remain outside conventional PI protection. When those uninsured consequences accumulate alongside captive reserve requirements and retained liabilities, the burden can extend beyond the operating partnership. International support may become necessary even without an automatic contractual obligation to absorb the underlying loss.
PwC and Evergrande: From audit failure to capital event
In 2024, PwC’s Mainland China firm received regulatory penalties totaling RMB441 million and a six-month suspension.[1] In April 2026, Hong Kong’s Accounting and Financial Reporting Council imposed an additional HK$300 million penalty and a six-month restriction on specified public-interest-entity engagements. PwC Hong Kong separately agreed to establish a HK$1 billion compensation arrangement for eligible independent minority shareholders of Evergrande.[2][3] The identified commitments totaled approximately US$228 million at the exchange-rate assumptions used in the September analysis, before recoveries, legal costs and entity allocation.
Evergrande's liquidators are pursuing approximately RMB57.9 billion in contested litigation against PwC entities, including approximately RMB38.1 billion claimed against PwC International. These are disputed claims, not established liabilities. PwC International has sought to be removed from the proceedings.
Reporting also identified departing Mainland China audit clients representing approximately RMB561 million in annual fees.[5] The resulting loss of earnings contribution would depend on the profitability of those engagements, replacement work and other offsets. It is not an insured settlement. Reports of PwC Hong Kong preserving funds otherwise expected for partner distributions similarly indicate liquidity pressure, although retained distributions are not themselves a new economic loss.[6]
KPMG Australia: Commercial impairment before a large settled claim
KPMG Australia’s Lendlease-related controversy involved allegations about confidential client information and the treatment of a whistleblower. The firm acknowledged shortcomings in its response and undertook governance changes.[7]
It lost its longstanding Lendlease audit relationship; Macquarie withdrew its planned appointment of KPMG as auditor; and Australian government procurement restrictions have been extended until February 28, 2027.[8][9][10]
KPMG Australia reported FY2026 revenue of A$2.257 billion, a 13% decline in average equity-partner remuneration and restructuring involving approximately 360 employees and 27 partners. Consulting revenue declined 16.9%, though market weakness and lower government spending also contributed.[11]
It would be incorrect to attribute all this deterioration to the controversy. Nevertheless, lost engagements and constraints on new work illustrate how governance problems can impair future contribution independently of insurance claims.
ABC News reported in August 2026 that KPMG Australia had sought financial assistance from KPMG International. The amount, terms and completion of any assistance were not publicly established.[12] The report highlights the possibility that local governance deterioration can generate liquidity demands beyond a member firm’s available capital, without proving that a particular covenant breach was prevented.
The next pressure point: Excess professional indemnity insurance
Professional-services PI insurance experienced substantial pricing corrections in 2020–2022. Subsequent broker analysis has emphasized claims history, retentions, insurer participation and risk quality.[13][14][15]
Public evidence does not establish that excess coverage is generally unavailable to the Big Four. The concern is more specific: a firm facing governance deterioration may confront higher attachment points, reduced insurer participation or increased captive retention at precisely the time its earnings and capital flexibility are under pressure.
GCS can therefore become self-reinforcing: the earnings that generate partnership capital weaken just as the capital required to sustain the business increases.
The missing measure: How long did management know?
Traditional underwriting measures claims, litigation and settlements after the underlying conditions have matured. It provides less visibility into when warning signals first arose, who received them, how quickly they reached decision-makers and whether corrective action worked. Those questions are central to prevention and to credible risk assessment.
HeardSafe’s proposed Trust Record is designed to document frontline concerns, recurring patterns, escalation and remediation. Such evidence could complement historical claims data for captive managers, international risk committees and excess insurers. It does not guarantee lower premiums or eliminate liability; it offers a way to evaluate whether tomorrow’s governance risk differs from yesterday’s claims history.
The next fiduciary responsibility
The financial consequences of governance failure should no longer be assessed solely by settlement size or insurance recovery. PwC illustrates regulatory commitments, contested litigation and capital preservation. KPMG Australia illustrates impaired client relationships, future earnings and possible liquidity support before a major settled liability. Both show why a firm may be insured against certain professional claims and still face severe Governance Capital Stress.
The defining question for Big Four leadership is not only how much insurance the partnership can purchase, but what evidence it can produce that governance deterioration was identified, escalated and corrected before loss of trust became a lasting impairment of partnership capital.
Endnotes
PwC, Global Transparency Report 2024, p. 50; Mainland regulatory actions, September 2024.
Hong Kong Accounting and Financial Reporting Council, PwC/Evergrande enforcement announcement, April 23, 2026.
Hong Kong Securities and Futures Commission, shareholder compensation arrangement, April 23, 2026.
PwC International must face trial of Evergrande scandals claims: Hong Kong High Court | South China Morning Post
Financial Times, departing PwC Mainland China audit clients and fees, July 2024.
Reuters, PwC Invests in ‘High Quality’ Business in China After Record Fine, Internal Memo Says, September 16, 2024.
Reuters, KPMG Australia whistleblower controversy and parliamentary scrutiny, August 13, 2026.
Lendlease, Annual Report 2025, auditors’ remuneration.
Macquarie Group, Update on Audit Tender, August 26, 2026.
Australian Department of Finance, Further update on procurement of goods and services from KPMG | Department of Finance
KPMG Australia, FY26 Result and Business Streamlining, August 24, 2026.
ABC News, KPMG to Cut Almost 400 Jobs from Australian Arm as It Loses Contracts After Audit Leaks Scandal, August 24, 2026.
Aon, Pricing Accountants’ Professional Indemnity Insurance: The Broker’s Perspective, June 2026.
Aon, Professional Service Firm Risk and Human Capital Environment and Indications for 2025, December 2024.
Aon, Professional Service Firms in 2025 and Some Thoughts on the Future, December 2025.
Methodology: GCS is a proposed analytical framework, not an audited measure. Its dimensions are not necessarily additive; contingent claims, recognized losses, funding support and insurance recoveries must be separately identified. This draft is based on research assembled September 28, 2026.
About Steve Hourigan

Steve Hourigan is founder and CEO of HeardSafe, Inc., which builds governance signal infrastructure, including systems of the kind described in this article. He has served on more than twenty boards.
His book in progress, The Trust Record, examines 13 governance failures through the lens of signal latency: the time between when an organization first knows something and when someone with authority acts on it. Using a timed framework (T0–T5), it traces how each warning travelled, stalled or was reclassified on its way up, and argues that most failures come from routing rather than malice or ignorance. One chapter is devoted to KPMG Australia.
Firms need a timed record of their own warnings because every regulator, court and liquidator eventually asks the same question: what did you know, and when? Most firms can only answer after the event, reconstructed under pressure; The Trust Record shows how to measure the answer while there is still time to act on it.
This article is part of the Big4News Investigations & Analysis series, which examines the structural forces shaping Deloitte, PwC, EY and KPMG.
For more cases involving the Big Four audit firms, explore our Global Big Four Scandal Timeline, which documents major controversies, regulatory investigations, enforcement actions and corporate scandals involving the firms around the world.