

Long before Deloitte, PwC, EY and KPMG became the Big Four, eight accounting firms dominated the audit of the world’s largest companies. Their rise was closely intertwined with industrialisation, the growth of public capital markets and the development of the modern corporation.
The accountants follow the money
In the aftermath of the Civil War (1861–1865), the American economy started to industrialize at breakneck speed. British financiers invested heavily in the market, pouring hundreds of millions into industries such as mining, iron and steel production, and railroad construction—and they demanded that their accountants oversee their foreign financial interests.
This led to four hundred British chartered accountants crossing the Atlantic between 1875 and 1914 to scrutinize these investments, landing in cities such as New York, the financial epicenter of the country, and Chicago, the Midwest railroad hub. Some of them stayed, setting up practices in the US.
Both Price Waterhouse and Deloitte opened their first permanent US offices in New York in 1890, followed soon after by branches in Chicago. The timing was propitious, coinciding with a major shift in the securities market in the country.
The New York Stock Exchange (NYSE), which had been founded in 1792, had up to then mainly traded in stocks and bonds related to railroads. Industrial companies, such as processors of agricultural commodities, basic materials and emerging heavy and electrical manufacturing, had mainly been family-owned—the common perception being that they were much riskier enterprises to invest in than the tried and tested railroad business.
The situation changed dramatically in the last decade of the nineteenth century, when the robust economy created two concurrent phenomena. Demand for production capacity surged, creating a massive need for capital to keep up, while investors’ confidence was at an all-time high, so they became more receptive to stocks and bonds issued by industrial companies.
As the market for such securities became increasingly liquid, it created the opportunity for businessmen to finance and execute large-scale mergers and consolidations by issuing stocks to raise the capital required for acquisitions, or by offering stock in the newly combined entity to owners whose companies were being taken over.
America’s merger boom
This dynamic fueled the Great Merger Movement, with close to two thousand companies merging between 1895 and 1904, in the process creating the giants that would dominate the American—and eventually the global—economy in the twentieth century.
An excellent example is the series of mergers, orchestrated in the main by financier J. P. Morgan, that created U.S. Steel, the world’s first billion-dollar corporation.
The consolidation started in 1899, with the coalescing of over a dozen barbed wire and steel manufacturers to form the American Steel & Wire Co., as well as the amalgamation of over fifteen pipe and tube makers to form the National Tube Company.
These merged entities were then swallowed whole in 1901, in the largest merger of them all, incorporating Carnegie Steel, Federal Steel, National Steel and many others, including American Tin Plate, American Sheet Steel, American Bridge, and Lake Superior Consolidated Iron Mines.
The resulting industrial behemoth incorporated the complete process from the mining of raw materials to the production of steel, and on to the manufacturing of final products such as wire, tin plate, tubes and bridges.
These mergers created a massive demand for auditors, who were engaged to conduct a detailed due diligence of the companies in question—in most cases they inspected five to ten years’ worth of financial records, issued financial statements for the period, and subsequently devised an accounting system for the newly formed entities.
This required much accounting innovation, for nothing on this scale had ever been seen before.
In the case of US Steel, for example, Arthur Lowes Dickinson of Price Waterhouse compiled consolidated accounts for the year ended December 31, 1902, giving stockholders full oversight over the affairs of the massive conglomerate. The resulting financial statements were dubbed by Scientific American as “the most complete and circumstantial report ever issued by any great American corporation.”
The firms take shape
The flood of work inevitably attracted other accountant entrepreneurs, both from the UK and homegrown.
In 1895, Charles Waldo Haskins and Elijah Watt Sells, two American accountants who had been appointed by the Dockery Commission—the Joint Commission of the 53rd Congress—to assess federal accounting practices, founded Haskins & Sells in New York City.
The following year, the state pioneered mandatory examinations for Certified Public Accountants (CPAs), and Sells became one of the first accountants to qualify.
The firm grew rapidly, opening offices in cities with intense merger activity, as well as an international office in Britain: Chicago in 1900, London in 1901, Cleveland and St. Louis in 1902, Pittsburgh in 1903, and Baltimore in 1910.
In 1897, James Marwick and Roger Mitchell, Scottish immigrants, started Marwick, Mitchell & Company in New York.
Fourteen years later, in 1911, Roger Mitchell met William Peat, an English accountant with a practice in London, during a transatlantic voyage. The two men got on so well that by the time the ship made it to port they had struck a deal to join forces—forming Marwick, Mitchell, Peat & Co.
William Lybrand, Thomas Edward Ross, Adam Averell Ross, and Robert Montgomery, American accountants who had learned the ropes in the office of John Heins, a prominent Philadelphia public accountant, set up Lybrand, Ross Bros. & Montgomery in Philadelphia in 1898, expanding to New York, Pittsburgh, and Chicago by 1910.
Meanwhile, in 1900, George Touche, who had a well-established accounting practice in London, and John Ballantine Niven, a Scottish migrant who had previously been employed by Price Waterhouse, established Touche, Niven & Co in New York.
In 1903, brothers Alwin C. Ernst and Theodore Ernst founded Ernst & Ernst in Cleveland, Ohio. Theodore subsequently left the firm, while Alwin Ernst remained at its helm and expanded the practice across the United States.
Then in 1906, Arthur Young, yet another Scottish accountant, founded Arthur Young & Co. in Chicago—rapidly expanding into Kansas City, New York City, and Milwaukee.
And finally, Arthur Andersen, who had started his career at Price Waterhouse, and subsequently become a professor in accounting at Northwestern University’s School of Commerce, teamed up with Clarence DeLany in 1913 to acquire a small accounting firm in Chicago.
They rebranded it as Andersen, DeLany & Co. Five years later DeLany left the firm, which then became Arthur Andersen & Co.
The stage was set for the rise of the Big Eight firms that would dominate the American accounting industry through the twentieth century.
Accountants become advisers
British accountants operating in the US soon discovered that the business environment in the new world did not much resemble that of the old.
Professional connections were not formed at school or in gentlemen’s clubs: one had to hustle to bring in new clients. The US market was more entrepreneurial, merit-based, and aggressive. Referrals were important, but they were based on performance, not class-based networks.
Overt promotion, which was at the time anathema for the profession in Britain, was often required in the US, particularly in the early days when accounting firms were still unknown.
Providing value for money was also very important, and prospective clients did not hesitate to negotiate for discounts, pushing down profit margins. Repeat business was not guaranteed, however excellent the service provided, for a client would switch accountants if they could get a better deal.
This was particularly important after 1904, when the tsunami of mergers died down and accounting firms had to go out and win new business—in some cases taking on engagements that pushed the boundaries of what had up to then been viewed as being the role of the accountant.
In 1907, for example, Deloitte and Price Waterhouse were engaged by Congress to conduct an efficiency study of the US Postal Service. The two firms suggested several changes to the organisation’s internal processes, including the adoption of basic adding machines to improve accuracy and save time. They also recommended shifting to cost accounting.
This marked the beginning of a new era, with accountants increasingly called upon to conduct “systems work,” advising clients on how to improve efficiency and implement effective internal controls.
Then in 1909 the US government introduced corporation tax, imposing a 1% excise tax on corporate net income above $5,000, followed by individual income tax in 1913.
This created a new opportunity for accountants, who were called upon to calculate taxable income and payments due.
The experience they gained in tax advisory became crucial when America joined World War One and Congress passed the War Revenue Act of 1917, which introduced steep excess-profits taxes on corporations to fund the war effort.
Accountants played a central role in helping clients determine ‘excess’ profits by establishing pre-war baselines, adjusting invested capital, and ensuring compliance with complex deduction rules. This work cemented the transition of public accountants into essential tax advisors for their clients.
Audit becomes a public franchise
The next great boost to the profession came not from corporate expansion, but corporate collapse.
In the years following the Wall Street Crash, while the country was still in the grips of the Great Depression, Congress sought to untangle the causes of the devastation, spearheaded by a Senate Banking Committee probe led by Ferdinand Pecora.
Their findings made for grim reading.
The soaring stock prices of the twenties had often been orchestrated by bankers or groups of company insiders who pooled resources to purchase stocks in bulk and push up prices, enabling them to then “dump” their holdings at enormous profits.
Insider trading based on information not in the public domain was rampant, and it was also common for investment bankers to have lists of preferred clients, such as politicians or other influential men, who were given the opportunity to purchase newly-issued stock at below-market prices, enabling them to turn an immediate profit.
And finally, and most crucially, stock sales prospectuses provided to investors often overstated earnings, through accounting tricks such as recognizing as-yet unearned income, and did not disclose material risks such as affiliate losses, deliberately misleading the investing public.
The findings of the Pecora Commission led to the U.S. Securities Act of 1933, often referred to as the “truth in securities” law, and the Securities Exchange Act of 1934, which mirrored the UK Companies Act of 1900 by mandating audited financial disclosures by listed companies—once again positioning auditors as the foundation on which trust in the financial markets was to be rebuilt.
That system of public-company audit oversight would eventually evolve further through the creation of the PCAOB after Enron and Arthur Andersen.
The great majority of companies listed on exchanges such as the NYSE were already using external CPAs to audit their financial statements, but now doing so was no longer a voluntary choice designed to reassure investors—it was a federal requirement.
This gave auditors a highly lucrative and prestigious public franchise—giving them a master key to the inner sanctum of listed companies, and unfettered access to the C-suite and other important corporate decision-makers—but with it came civil liability in cases where their certified statements contained material misstatements or omissions.
Over the following years the SEC introduced regulations defining the format and contents of the financial statements to be filed by public companies, and worked with the American Institute of Accountants (AIA) to start formalizing auditing standards.
The fraud that changed auditing
Everything appeared to be on track—until the McKesson & Robbins scandal erupted on December 5, 1938.
The company had been taken over in the mid-1920s by convicted felons Philip Musica and his brothers, operating under false names. Over the following decade they perpetrated an audacious fraud, right under the nose of their auditors, Price, Waterhouse & Co.
The brothers created fake paper trails that inflated company assets by over nineteen million dollars, claiming that massive inventories of crude drugs were stored in Canada.
However, it was nothing but smoke and mirrors—the Canadian company they claimed to work with, W.W. Smith & Co, did not exist, and neither did the inventory of drugs.
Price, Waterhouse & Co had taken their claims at face value, and in fact it was an internal accountant, not the auditors, who first uncovered evidence of fraud, leading the board to initiate a full investigation.
The external auditors had not physically inspected inventories, confirmed account receivables, or checked that the Canadian agency actually existed—but in all fairness these were not issues that auditors checked at the time.
The fraud sent shockwaves through the entire financial ecosystem, for if it was possible to hoodwink auditors so easily then the entire edifice of trust in the markets was built on quicksand.
The SEC and AIA moved rapidly, and in October 1939 the institute published the “Extensions of Auditing Procedure,” designed to cover the gaps exposed by the brothers Musica’s fraudulent endeavours.
Auditors were now expected to get external validation of all the information provided by company management.
This included physically inspecting inventories; directly confirming balances with banks, debtors and creditors; and testing internal controls to improve the chances that fraudulent transactions would be identified. The new guidelines were the first step towards the formation of the Generally Accepted Auditing Standards (GAAS).
The revised audit procedures required auditors to become intimately acquainted with their clients’ business processes, internal controls, profit drivers and operational weaknesses.
They were also very labour intensive, making it difficult for small audit firms to conduct comprehensive audits of large companies, particularly when the audit involved overseas subsidiaries—creating a barrier to entry and helping to entrench the position of the large accounting firms that increasingly dominated the audit of major US corporations.
The Big Eight
By the middle of the twentieth century, auditing the world’s largest corporations required scale, specialist expertise, large teams of trained accountants and an increasingly international footprint. The firms that could provide those resources became progressively harder for smaller competitors to displace.
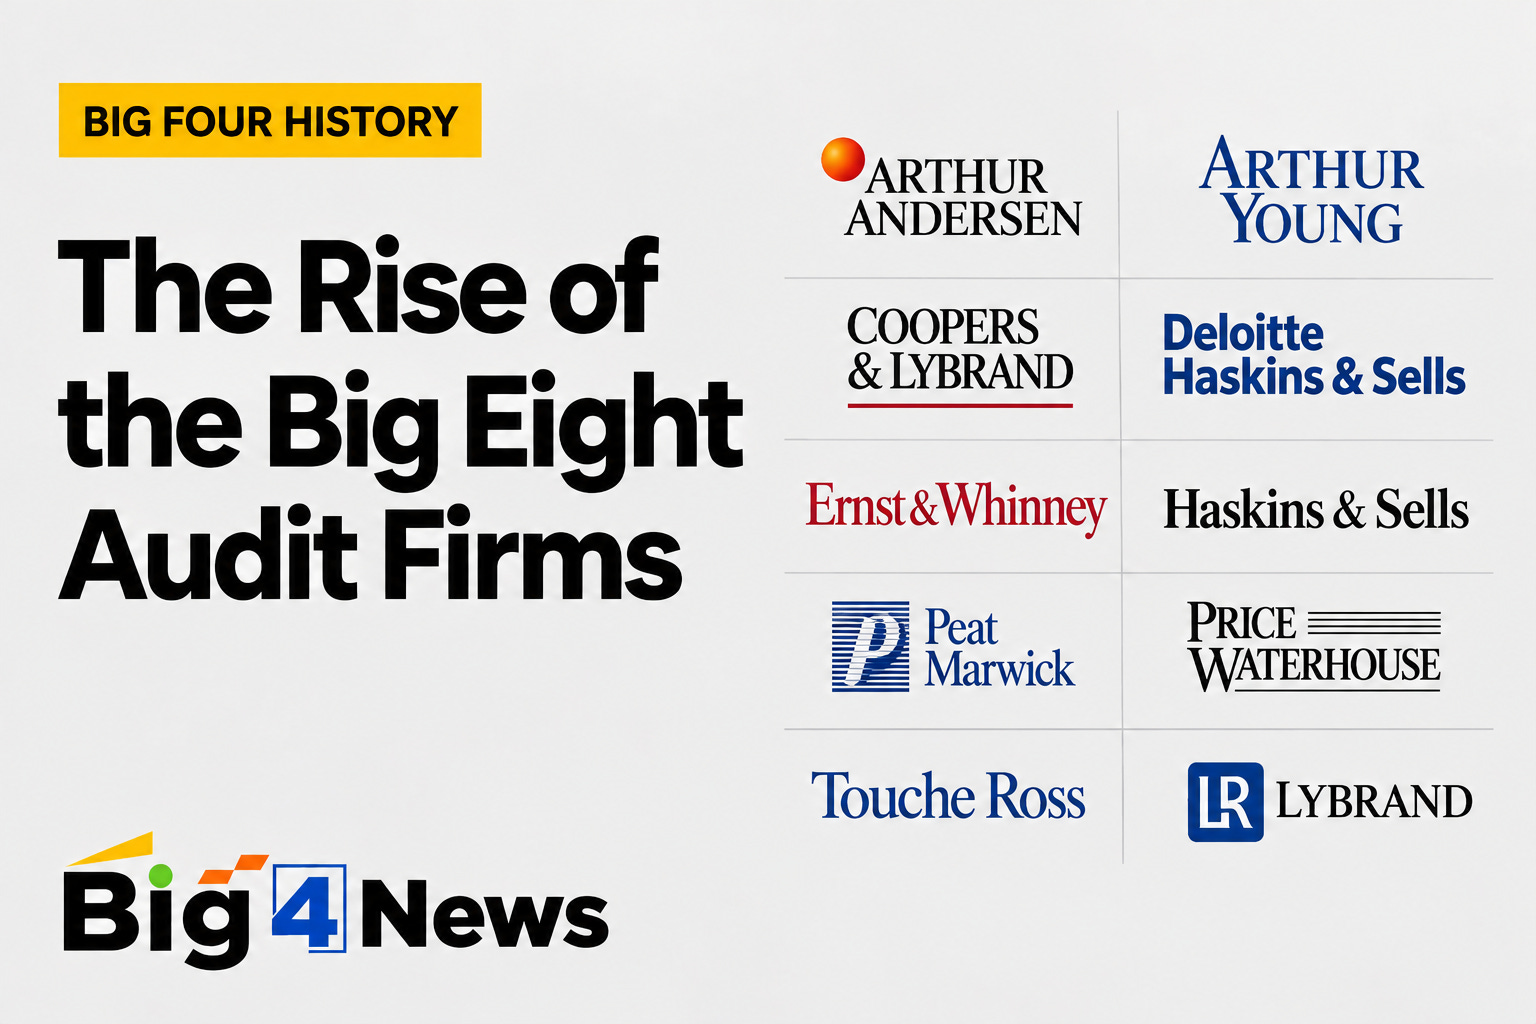
By 1960, eight firms had emerged at the top of the US accounting profession. Around this period they became known collectively as the “Big Eight”
Price Waterhouse.
Haskins & Sells
Arthur Andersen
Arthur Young
Peat Marwick Mitchell
Ernst & Ernst
Lybrand Ross Bros. & Montgomery
Touche, Ross, Bailey & Smart
The names would continue to evolve as the firms formed alliances and merged with other practices, but the group of eight remained the dominant tier of the profession for more than two decades.
Their dominance would last for decades. But by the 1980s, changes in the economics of audit, rising litigation exposure, the rapid expansion of consulting and the increasing globalisation of their clients would push the firms into another period of transformation.
This time, instead of creating more large accounting firms, the pressures would cause them to combine.
The Big Eight were about to become the Big Six—and eventually the Big Four.
About Claudine Cassar
I’m a corporate anthropologist and former Deloitte equity partner. I sold my technology business to Deloitte in 2016 and led the Malta Consulting team for five years. I am the founder and editor of Big4News, which provides independent, clear analysis of PwC, Deloitte, EY, and KPMG — free from corporate spin.
Find me on LinkedIn, X, Instagram, or my author website.
Feel free to reply to this newsletter — I read every reply.